Financing partnership
Selling the Current Home and Financing the Next One Are Connected.
Dennis handles the real estate. A qualified divorce mortgage professional handles mortgage qualification and financing strategy. Neither answer is complete without the other.
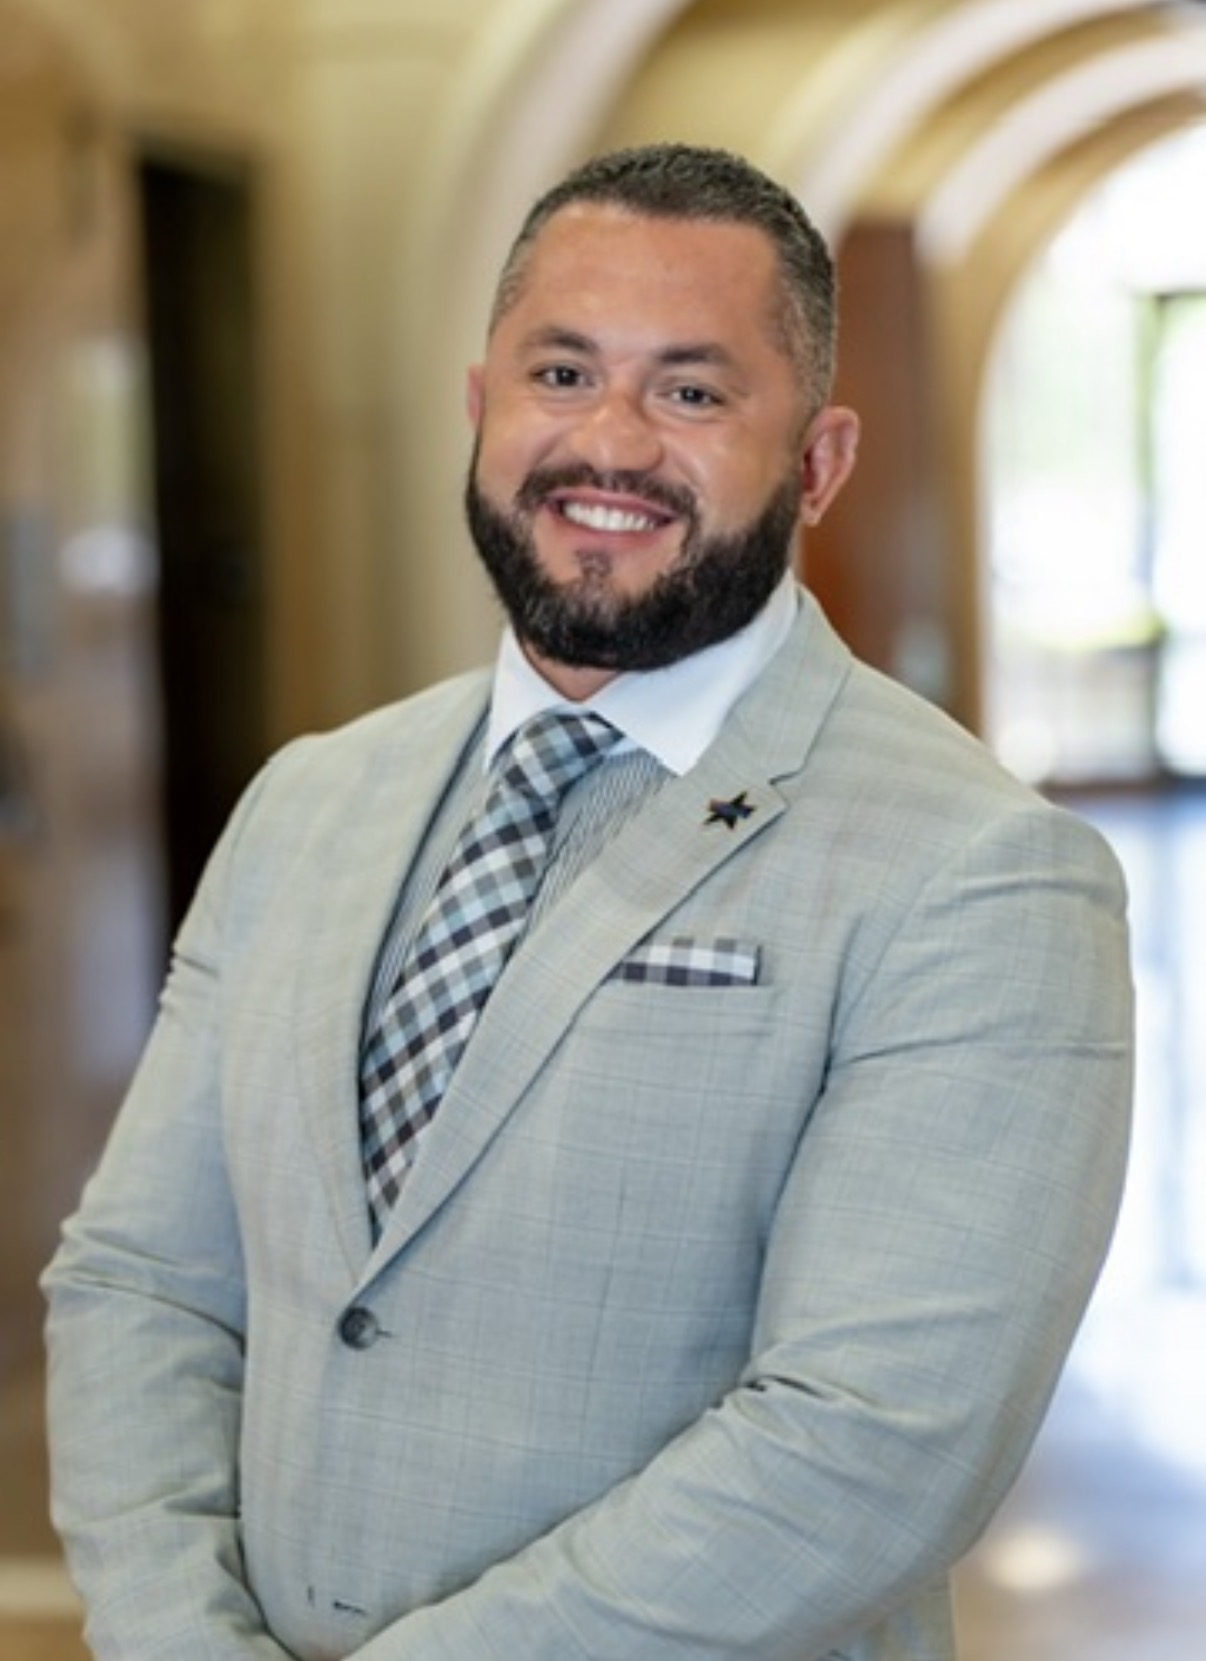
Mortgage partner
NJDivorceLender.com — Abdel Khawatmi
For divorce mortgage questions, Dennis refers to Abdel Khawatmi of NJDivorceLender.com, a New Jersey divorce mortgage professional focused on financing inside family-law matters.
- Divorce mortgage qualification
- Buyout and refinance feasibility
- Removing a borrower from an existing loan
- Support and maintenance income considerations
- Timing financing around a settlement
- Financing the next home after the sale
Why the two work together
A buyout is only realistic if the financing exists. A sale timeline only works if the next mortgage can close. When the real estate and mortgage sides trade accurate information early, both parties get answers they can actually plan around — instead of discovering a problem after an agreement is signed.
Scope stays clear
Dennis provides real estate information. The mortgage professional provides financing guidance. Attorneys provide legal advice. CPAs provide tax advice.
The group
The Divorce Alliance
Dennis is part of TheDivorceAlliance.com — a group of divorce-focused professionals who coordinate around the same matter so clients aren't left assembling advice from strangers.
One coordinated team
Real estate, mortgage and allied professionals who already work together.
Defined lanes
Each professional contributes inside their own licensure and expertise.
Fewer contradictions
Shared property and financing assumptions across the whole file.
Dennis Mark Interdonato is not a mortgage professional and does not provide mortgage, lending, legal, tax or financial advice. Referrals are provided for convenience; each party is free to select any professional. Mortgage products, qualification and terms are determined solely by the lender.
Common questions
Divorce mortgage and buyout questions
Educational information only. Nothing here is legal, tax, mortgage or financial advice.
Can I refinance the marital home into my own name?
That depends on income, credit, equity and loan program guidelines, and on what the divorce agreement says. A divorce-experienced mortgage professional evaluates that; a Realtor cannot answer it.
How is a buyout of the other spouse calculated?
Typically it starts with an agreed value for the property, subtracts payoffs and any agreed costs, and applies whatever split the parties or the court set. The property value side is real estate work; the loan structure and the legal split are not.
Why coordinate the Realtor and the lender in a divorce?
Because the sale timeline, the buyout timeline and the next-home timeline all depend on each other. Coordinating them early prevents an agreement that the financing cannot actually support.
Next step
The Divorce Is Complicated Enough.
The Real Estate Process Doesn't Have to Be.
When the marital home becomes part of a divorce, the goal isn't to create another fight. It's to create a clear, professional process for evaluating, preparing, marketing and selling the property.
One Home. Two Futures. One Clear Process.